



Our Recommended Insurance Solutions
The effective way to secure your family’s future

Schedule a call Click here

Give missed call to buy +91-9980970424
Contact Us

Login
 Customers

 Employees
 Partner
The effective way to secure your family’s future
The effective way to secure your family’s future
Term Plan
UIN:UIN: 101N145V08
Looking for complete protection under one plan at affordable cost along with tax benefits1
1 Crore Term Insurance @ Rs.21/day***
Get back your premiums at zero cost via Smart Exit Benefit Option2
Buy Online and get 7% discount6
Death Benefit paid in advance on diagnosis of Terminal illness3
Savings Plan
UIN:UIN: 101N134V26
Looking for safe financial instrument which provides alternate source of income
Save tax upto 46,800/-
Guaranteed** Income4 for period of 25 or 30 years
Get Back Premiums as Guaranteed** Lumpsum Benefit4 on maturity
Life Cover to protect your family
ULIP Plan
In Ulip Plan, the investment risks in the investment portfolio is borne by the policyholder
UIN:UIN: 101L103V03
An insurance cum investment plan with loyalty additions and multiple fund options to help you optimize your investment
Get option of 14 different Funds to invest your money
Choose from 12 Funds to optimize your investment returns
Customize your premium payment options – Single, Limited or Regular
Choose from 3 convenient Benefit
3 Questions, Tailored Plans
Answer 3 simple questions and find the best suitable plans as per your goal!
Life Insurance is a contract between a life insurance policy holder and an insurance provider. As per the contract the insurance provider promises to pay the beneficiary a sum of money upon the death of the policy holder during a certain period. The contract is applicable only when the policy holder has paid all premiums within the predefined period.
Depending on the contract, the policy holder is also eligible for a sum of money in events of terminal illness or critical illness as per the terms & conditions of the life insurance policy.
We help you to choose best insurance plan based on your needs
Our expert will assist you in buying a right plan for you online.
Reach us between 9 AM - 10 PM IST.
For existing policy related assistance, click here.
A certified expert of HDFC Life will help you.
99.68% Claim Settlement Ratio
For FY 2024-2025
~5 Cr. Number Of Lives Insured
For FY 2024-2025
Disclaimer: By submitting your contact details, you agree to HDFC Life's Privacy Policy and authorize ...Read More
99.68% Claim Settlement Ratio
For FY 2024-2025
~5 Cr. Number Of Lives Insured
For FY 2024-2025
Let’s explore the types of life insurance as per your financial needs:
Term insurance is the simplest form of life insurance that provides financial protection against death for a specific period. Since term life insurance is pure life insurance its premiums are affordable. Ideally you should get a term plan as early as possible as its premiums increase with age. Along with your term insurance plan you can avail additional coverage with add-on riders, for example if you want to get critical illness insurance you can get the critical illness rider. You can also opt to get all your premiums back after the term of the policy in case you survive through term insurance with return of premium.
A Unit Linked Insurance Plan (ULIP) is a type of life insurance that combines protection with investment. With a ULIP, you get life coverage and the chance to invest in market-linked options, which can potentially increase your money over time. It also offers tax benefits as per your income tax slab and the flexibility to switch between different investment funds. A ULIP calculator helps you figure out how much coverage you need and how to split your money between insurance and investments.
The endowment policy provide guaranteed returns and protection of life insurance. By choosing an endowment plan, you can experience extensive coverage with the opportunity to save regularly. Thus, a policyholder expects to achieve a lump sum once the policy matures. To calculate the final payout of this policy you can use the savings calculator. In case of your sudden death during the policy tenure, your nominee will be eligible for death benefits.
Retirement plans or pension plans are investment plans designed to ensure you’re financially secure when you retire. They let you invest money while you’re working, building up a savings fund that you can use when you stop working. Investing in retirement plans is a smart, disciplined way to prepare for a comfortable and worry-free retirement.
Child insurance plan helps secure your child’s financial future by saving for education and marriage costs. Child plans provide maturity benefits when the child turns 18, either as a lump sum or in yearly payments. They also include insurance for parents, offering financial support if the insured parent passes away during the policy period.
It is a type of savings plans where you invest in a participating plan you will receive dividends and bonuses derived from the profits. These payments are usually made annually. There are several ways in which you can utilize and receive dividends and bonuses if you hold a participating policy:
These benefits are in addition to the regular maturity benefits that are guaranteed by the life insurance company. If applicable, some insurers offer terminal bonuses upon maturity along with paid-up additions.
Whole life insurance provides comprehensive life insurance coverage till 100 years of age. It's also known as permanent life insurance because it offers life cover for your family when you are not around. It's a reliable way to ensure your loved ones are financially secure and to plan for your own financial goals.
Annuity plans ensure you get regular income after you retire, helping you build savings for the future. These financial products provide steady payments throughout retirement.
Money Back Policy is a type of life insurance plan that offers both life cover and regular returns during the term of the policy. It combines the benefits of life insurance and investment, providing financial protection along with steady returns at specific intervals.
Let’s explore the various benefits of life insurance:
Upon the demise of the policy holder the beneficiary of the policy receives a sum of money as the death benefit. Objective of death benefit is to provide financial support to the beneficiary in case of the policy holder’s absence.
Life insurance is one of the financial tools that offer dual tax benefits. For the premiums you pay, you can avail tax deductions under Section 80C of the Income Tax Act10. Also, the maturity and death benefit are tax-free under Section 10(10D) of the Income Tax Act10.
There are types of life insurance that help in wealth creation along with financial protection. Unit-linked insurance plans (ULIPs) and endowment plans can help grow your wealth in the long term as per your risk appetite. In the case of ULIPs, returns are linked to the markets and in the case of endowment plans the returns are guaranteed. An investment calculator can help you evaluate the estimated returns of an investment plan like ULIP or endowment plan.
Life insurance plans other than term life insurance offer maturity benefits at the end of the term of the policy. For example, if you get a ULIP for 15 years then at the end of 15 year you will receive the maturity benefit.
Riders are add-ons that help enhance the financial protection provided by your base life insurance. You can choose to opt for riders for an additional premium. You can customise your requirements by opting for various riders, such as accidental death rider, waiver of premium rider, accidental disability rider, critical illness rider, etc.
"Thanks to HDFC Life, I am now able to pursue my education abroad and fulfill my parents' dreams"
Sartajbir Singh
Batala, Punjab
Caringwith
Pride
Sartajbir Singh
Batala, Punjab
Caringwith
Pride
" I want to express my gratitude to Mr. Nishant Sharma from HDFC Life for his invaluable assistance during my difficult time. As an 18 yr old, managing the death claim of my mother while my father was working abroad, I was distressed. Nishant not only helped me with all the documentation for claim submission but also provided unwavering support throughout. His guidance made a significant difference in navigating the claims procedure. The claim closure time efficiency was an additional source of relief during this challenging period. I must emphasize Nishants exceptional character and dedication. He truly went above and beyond to help me out. Thanks to HDFC Life, I am now able to fulfill my parents' dreams."
IMT/MC/06/23/1951
"HDFC Life's prompt service amazed me as I received the claim amount within 24 hours"
Anoop Chahar
Agra, Uttar Pradesh
Caringwith
Pride
Anoop Chahar
Agra, Uttar Pradesh
Caringwith
Pride
" I am grateful to Mr. Harish Rawat and HDFC Life for their incredible assistance in processing my father's death claim. HDFC Life's prompt service amazed me as I received the claim amount within 24 hours of applying. Mr. Harish went the extra mile by personally arranging the required hospital discharge summary required for claim submission. I sincerely thank Mr. Harish and HDFC Life for their outstanding dedication and support. Their commitment to their responsibilities and customers is truly commendable, and I am forever grateful for their exceptional service."
IMT/MC/06/23/1951
"In addition to the quality service, the transparency displayed by HDFC Life has instilled confidence in me as a customer"
Parna Acharya
Batala, Punjab
Caringwith
Pride
Parna Acharya
Batala, Punjab
Caringwith
Pride
" The seamless and efficient claim processing of my late husband's HDFC Life Term plan has provided us with the much-needed financial stability during this challenging time. Moreover, the personalized attention and empathy shown by the staff has left a lasting impression on me. I would like to express my gratitude for timely communication throughout the entire process by Mr. Subhadip. His prompt updates and clear explanations helped alleviate my concerns and kept me informed at every step. In addition to the quality service received, the transparency displayed by HDFC Life has instilled confidence in me as a customer. Thank you for being there for me and my family during this difficult journey."
IMT/MC/06/23/1951
HDFC Life is one of India's leading life insurance company offering a range of individual and group insurance solutions that meet your various needs such as Protection, Pension, Savings & Investment, Health and more.
New Business
Across in India
In FY 24-25
In FY 24-25
As per HDFC Life Integrated Annual Report FY 2021 - 2022
Life Insurance is a legal contract between the policy holder and the insurer. Here are some aspects that will help you understand life insurance better:
Life Insurance is an agreement between the policy holder and an insurance company. The policyholder pays a premium to obtain the desired life cover as per the terms & conditions of the agreement. In case of death of the policyholder the beneficiary receives the death benefit.
...Read More
The premiums of a life insurance are dependent on a few factors, such as type of life insurance you purchase, term of the policy, premium paying term, your age, your gender, the insurance company selling the policy, and your overall health, wellness, and family history.
...Read More
As far as the claim is concerned, if the insured passes away during the policy's tenure, a death benefit is paid to the insured's designated nominee in an amount predetermined by the insurer. Making a claim for this is a fairly easy process. A claim can be initiated online, through text message, email, phone at the insurer's call centre, or in person at a branch office. To expedite the claim processing, it is best to notify the insurer as soon as the required paperwork is prepared. Do research on the insurer's claim settlement ratio prior to buying a life insurance policy. This indicates the possibility that your claim will be resolved.
...Read More
As per the payout option selected by the policy holder the beneficiary receives the death benefit amount on the demise of the policy holder.
Let’s understand how a life insurance works with the help of an example:
Ravi a 25-year-old health male decides to get a life insurance (HDFC Life Click 2 Protect Super (Life option) (UIN:101N145V08)) for a life cover amount of 1 crore till the age of 55 years. As per his age, gender, medical conditions and lifestyle habits the premium amount that he needs to pay is Rs.706 per month for a 1 crore term insurance. In case he dies by the time he turns 60 his wife who is the beneficiary of the life insurance receives the death benefit amount of 1 crore as per the payout option selected at the start of the life insurance.
...Read More
Life insurance is an essential financial instrument as unlike any other investment option it provides a unique benefit of life cover. Let’s deep dive into reasons as to why one should get a life insurance:
Life insurance offers an essential benefit of financial security unlike any other investment option. All types of life insurance provide death benefits to the beneficiary in case of death of the policyholder. The death benefit amount helps the beneficiary to take care of the financial needs in the policy holder’s absence.
...Read More
Along with financial security, life insurance also provides the opportunity to grow your wealth. There are various types of life insurance suitable for every stage of your life. Life insurance can act as an investment plan to fulfill different financial goals such as child’s education, retirement and others.
...Read More
Along with the life cover of your life insurance you can opt for add-on riders such as critical illness to avail additional financial protection in case detected with a critical illness. With a critical illness rider, you can get upfront payout if detected with a critical illness unlike a health insurance where you must claim the cover.
...Read More
If life insurance, you can avail several tax saving benefits under the income tax act, 19611. Premiums paid for life insurance are eligible for tax deductions under section 80C and maturity benefits are tax free under section 10(10D). You claim tax deductions for the premiums paid for critical illness rider under section 80D.
...Read More
Liabilities can pose serious financial stress to financial dependents in case of the primary breadwinner’s absence. The death benefit from a life insurance helps the dependents address any liabilities that might come on to them in case of the primary breadwinner’s death.
...Read More
Life insurance provides you with the opportunity to invest and build a corpus for your retirement. Pension plans are a type of life insurance that can provide you with a sustained regular income that can help you live a stress-free retirement. If you are behind in retirement planning, start with buying a life insurance plan. Investing in a plan at an early age will let you pay lower premiums. A pension calculator comes in handy to calculate your monthly pension needs for a stress-free retirement.
...Read More
An insured is an individual whose life is financially protected with life insurance.
An insurer is an entity that offers financial coverage and bears financial risk in exchange for premium payments. The insurer pays the death benefit in case of the insured’s death
Beneficiary is the person or entity legally designated to receive the insurance benefits, such as the death benefit, upon the insured’s death.
Death benefit is the amount paid to the beneficiary of the life insurance in case of death of the insured.
The premium is the amount the policy holder pays the insurance company in exchange for the life insurance coverage.
Policy tenure is the period during which life insurance offers financial coverage.
Premium paying term is the period for which policy holder pays the premium of the life insurance.
Maturity benefit is the amount an insured receives after the policy tenure.
Riders are additional benefits for enhancing the financial protection of a life insurance.
Claim is the process of intimating the insured’s death to insurer so that the insurer can process the payout of the death benefit to the beneficiary.
Life insurance can play a vital role at every stage of your life due to the flexibility it offers in term of benefits:
When you start your first job or early on in your career you have limited financial liabilities and greater risk-taking ability. At this stage with a ULIP you can invest in the market for the long term and grow your investment. Since you are young you should also get a term life insurance for a fixed and affordable premium because at an older age your premiums will be higher.
Having life insurance to cover your children's expenses in the event of your incapacity is essential if you have young children. ULIPs can help you secure your children's future while also building wealth. The cover includes paying for regular bills, schooling, marriage, and additional costs associated with raising children.
Life insurance such as retirement & pension plans help senior citizens to build their corpus for retirement. Annuity plans provide a regular source of income after retirement and ensure financial security.
For NRI’s life insurance include comprehensive life coverage and assist families with financial support in case of death due to an accident or critical illness. At the same time, life insurance also has benefits of taxes and flexibility in the payment of premiums to policyholders.
Life Insurance for self employed lends financial security to the families of the self-employed in case of their death. The death benefit amount covers the cost of immediate business overheads as well as everyday household expenses.
The first and the most essential step in financial planning is to assess your financial needs that are to be covered with life insurance. Life insurance can cater to multiple financial goals such as financial protection, growth of wealth etc. thus you need to identify the goal that your life insurance will fulfill. For example, if you have considerable financial responsibilities for your dependents then you can consider taking a 2 crore term insurance for enhanced protection.
...Read More
Depending on your specific financial need you need to choose the right type of life insurance. Let’s map some of the common financial needs with suitable life insurance:
- Term insurance is for financial protection of your dependents
- ULIP gives you the opportunity to grow your wealth by investing in the markets along with a life cover
- Endowment plan offers you 100% guaranteed15 returns on your investment along with a life cover
- Child Plan gives you the opportunity to invest and secure your child’s financial future
- Retirement & pension plan helps you save for your retirement
...Read More
Your life insurance premium depends on several factors. Taking all the factors into consideration the insurer decides on the premium amount for the desired life insurance cover. You can use the life insurance calculator to evaluate your life insurance premium.
...Read More
To enhance your life insurance cover, you can choose to opt for add-ons or riders catering to specific needs when you buy term insurance. For example, you can choose a critical illness rider along with your base life insurance so that you are covered against critical illnesses.
...Read More
There are several life insurance providers in India and selecting one can be challenging. While selecting you can check the life insurance provider’s reputation and other aspects that help you build trust.
...Read More
Life insurance company’s individual death claim settlement ratio tells you how likely they are to settle your nominee’s claim. You can check a company’s Individual Death Claim Settlement Ratio online. HDFC Life has an Individual Death Claim Settlement Ratio (CSR) of 99.50%.##
...Read More
At HDFC Life, we ensure a hassle-free and uniquely sensitive claim experience. We are always doing our utmost to enable faster settlement of claims, with our Claim Settlement Ratio reflecting this assurance.
Individual claims processed within 24 business hours for all claims over 3 years from the date of inception**.
*Individual death claim settlement ratio by number of policies as per audited annual statistics for FY 2022-23.
Check last 5 years claims trend.**Provided we have received all the relevant and required documents and no further investigation is required. Claim settlement process would be completed within stipulated timelines once the claim request is approved.
Know Moreis available for the following
T&C Apply
1. For all claims fulfilling above mentioned conditions, provided we receive all the required documents, the claim will be processed within one working day and decision will be communicated accordingly.
2. Investigation / Open title / Rival / Court involved Claims are excluded.
3. Policy duration at the time of event is at least >=3 years.
4. Saturday, Sunday, public festivals and non-NAV days (for ULIP) are excluded (not treated as a working day) ^Interest rate would be at 6.25%per annum.
#Documentation Details
Claim form, Nominee photograph, Pan card copy, Identity and Address proof of nominee. (If nominee is minor, documents of appointee to be submitted). Death certificate issued by competent authority for death registrations. Medical cause of death certificate. Cancelled cheque/copy with the name of nominee/appointee mentioned on it as per the passbook of the nominee/appointee. Past & current complete medical records including discharge/death summary, indoor case papers, investigation reports, consultation notes. In case of an accidental death, additional documents will be required. Post Mortem Report, Panchnama, Police Inquest report, First/Final Information report, Viscera/Chemical Analysis report.
There are several ways to assess the amount of life insurance you need. Here’s a simple and easy to remember method know as D.I.M.E. that can be applied by all to assess amount of life insurance:
First you need to account for debt that you have incurred and haven’t yet paid off. These can include auto loans, personal loans, credit card payment, and any other loans. The death benefit for your life insurance needs to cover your debts so that these don’t become a burden for your family in your absence.
...Read More
In case you are the primary earning member of your family then their livelihood is dependent on your income. In case of the death of the primary earning member the family can come under tremendous financial distress. As a thumb rule you should opt for a life insurance with a death benefit of 10-15 times of your annual income so that it can cover for your family’s living expenses.
...Read More
Payment towards mortgages or home loans is a significant portion of monthly expenses. In the case of absence of the primary earner the burden of paying off a large number of mortgages can cause financial distress on dependents. Thus, the death benefit opted for should be enough to cover of the loan amount.
...Read More
As parents we don’t want to compromise on our child’s education and want to provide the best for them. With rising education inflation, child education proves to be a major expense. In the event of your absence and a lack of life insurance your child’s goals might get compromised. Avoid such a scenario you should let a life insurance with a death benefit enough to cover your child’s goals.
...Read More
With so many considerations, let us help you to make easy decisions for your life insurance needs.
The premium amount depends on the life cover amount you have opted for. The higher the life cover amount, the higher will be your premium.
It is always advised that you should get life insurance as soon as you can since premiums increase with age. The older you are the higher the risk of covering you leading to a higher premium.
Men and women are biologically different, have different life expectancies and have different risks associated thus the premiums are different for men and women.
The longer you decide to financially cover yourself with life insurance the higher will be its premium.
The time for which you decide to pay your premium also plays a factor in the premium amount. There are options such as limited pay making it possible to pay your entire premium before the term of the policy ends.
Your lifestyle choices, such as smoking or drinking, can also impact your life insurance premiums.
Your medical history gives an indication as to how risky it is to financially cover you which in turn impacts the life insurance premium amount.
Some of our occupations tend to be riskier to financial cover than others thus impact life insurance premiums.
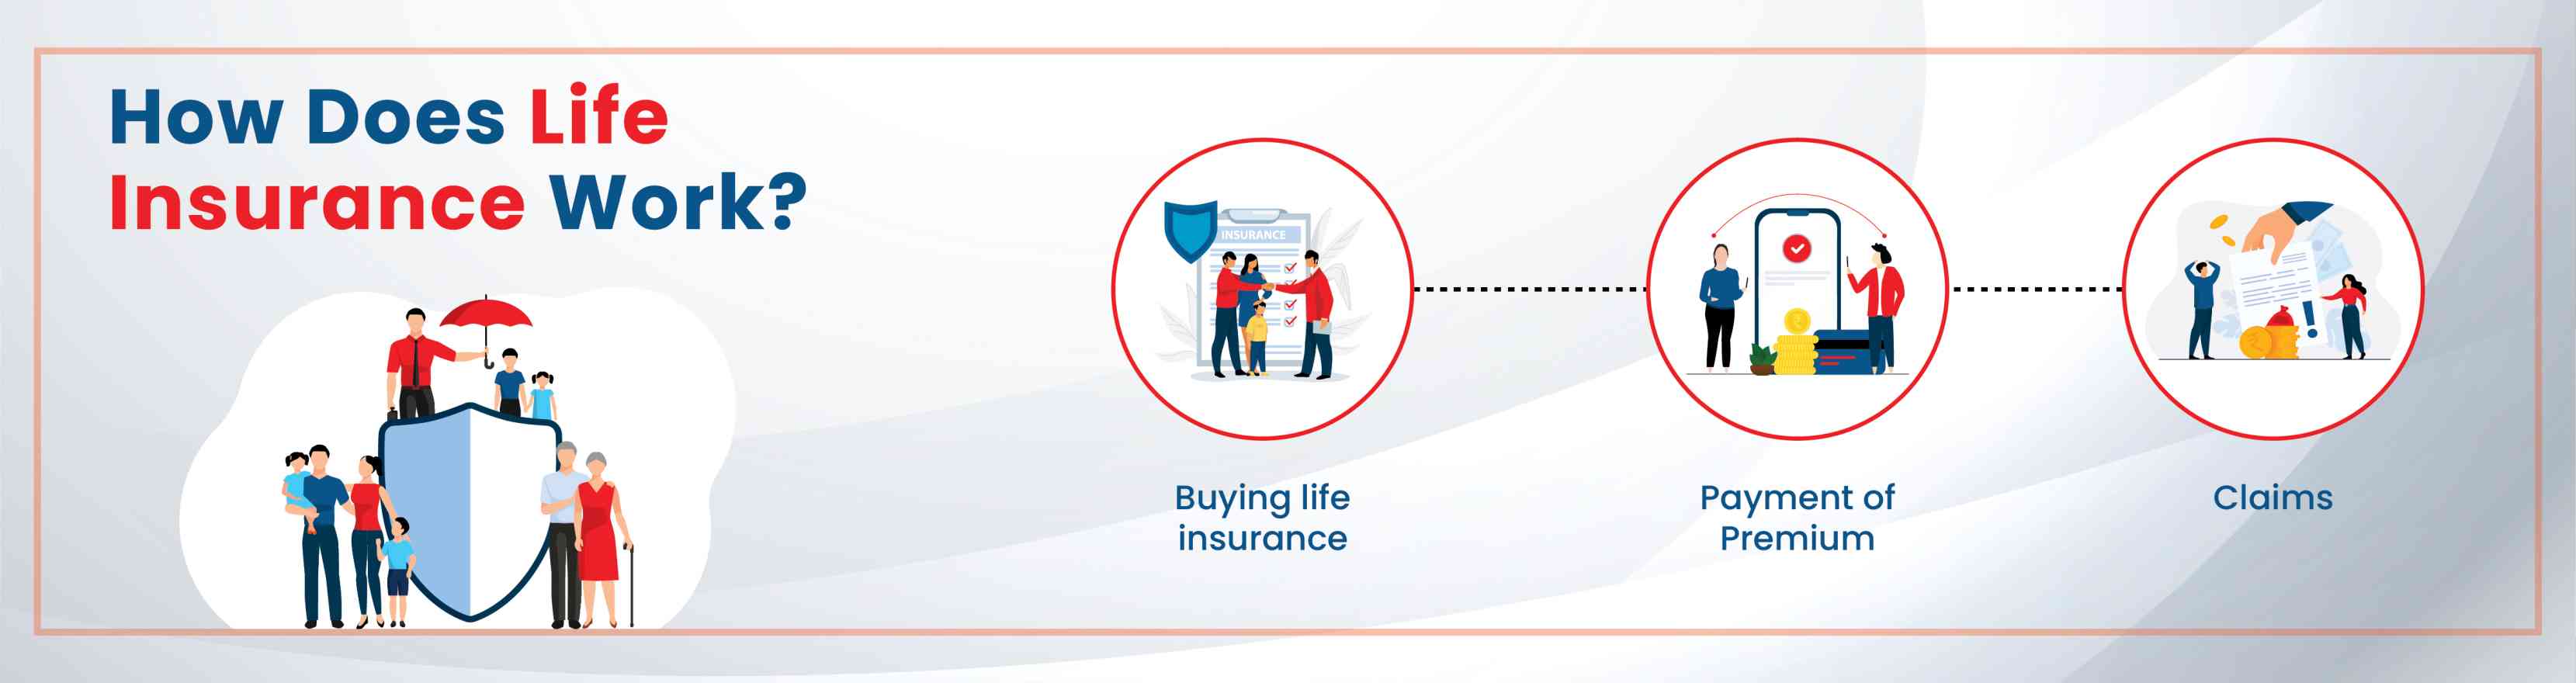
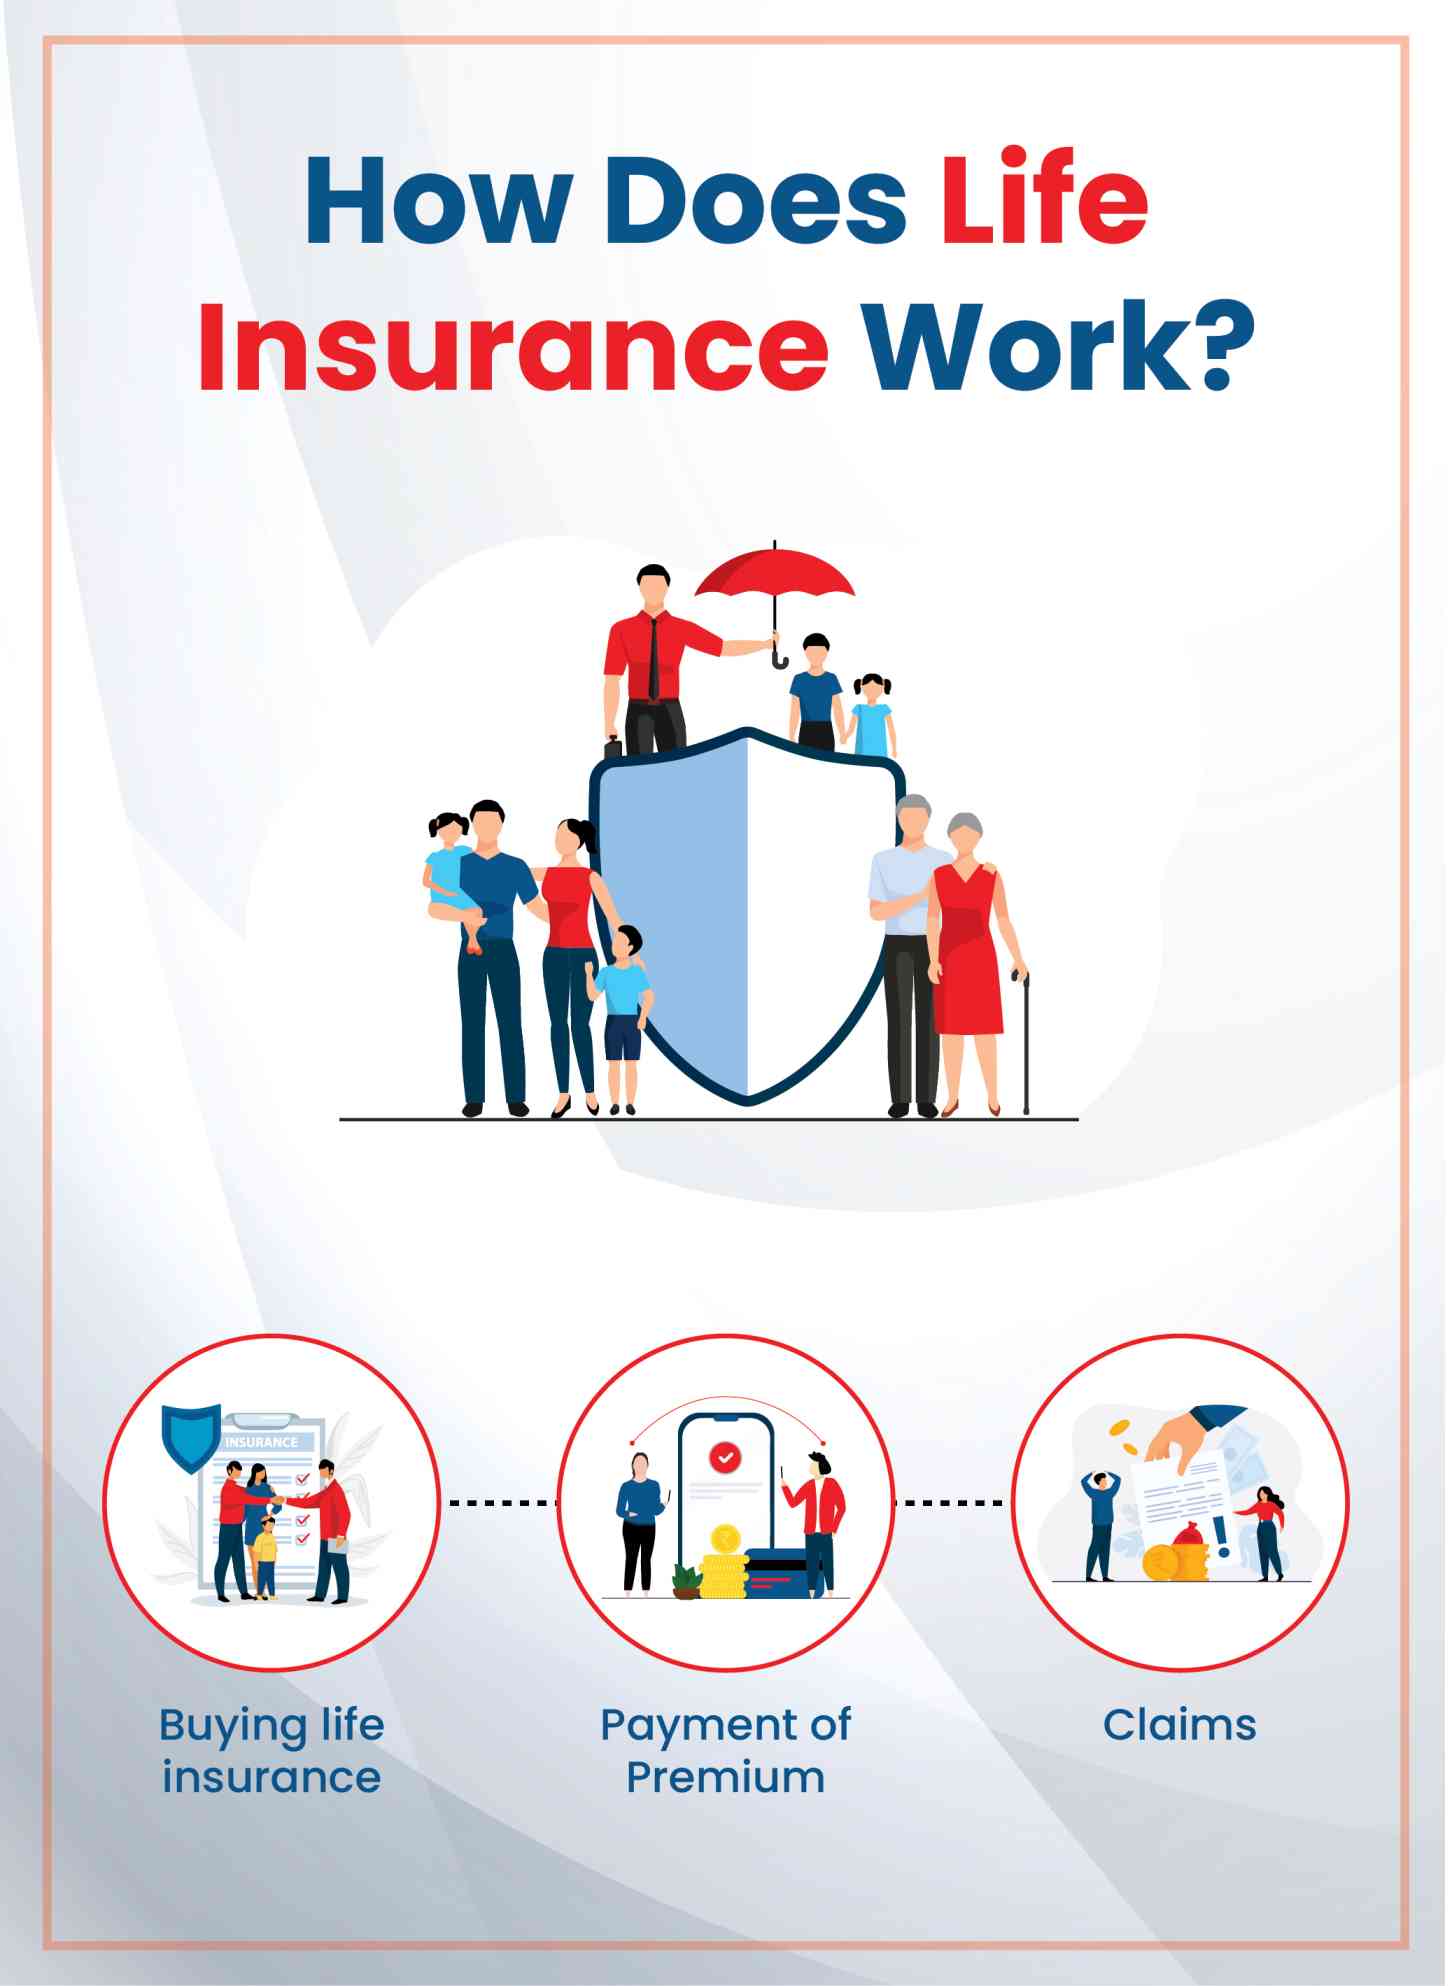
Buying a life insurance primarily consist of 4 steps -
The first step is to identify the financial need you want to address such as financial protection, child’s education, build your retirement corpus etc. Then you need to evaluate the amount required to meet your financial need and finally the estimate the premium amount that you will be able to pay for your desired life insurance.
...Read More
As per your financial goals you need to choose the life insurance:
- Term insurance: Financial protection of your dependents
- ULIP: Grow your wealth along with a life cover
- Endowment plan: Guaranteed returns along with a life cover
- Child Plan: Secure your child’s financial future
- Retirement & pension plan: Build your retirement corpus
...Read More
You can generate quotes from multiple life insurance companies and then decide as per what suits you the best.
...Read More
Once you have decided the type of life insurance and the company you need to –
- Provide the required information accurately
- If needed undergo medical examination
- Submit necessary documents
- Review your life insurance details
- Make the payment
...Read More
To buy a life insurance you will need to submit the following documents:
Buying life insurance online is easy and here is why you should opt to buy life insurance online:
By buying life insurance online you might be eligible for additional online discounts on your premiums.
You can buy life insurance from the comfort and convenience of your home. You can use easy to use calculators like the term insurance calculator to get an estimate of your premium amount.
Any information regarding your life insurance is available online on the life insurance company’s website and mobile app. Also, the entire process till the payment is on the official company platform making it secure.
HDFC Life Insurance provides flexible payout options catering to the needs of respective policyholders. Here are the different payout options:
This payout option offers a monthly payout in installments to take care of the monthly financial needs of the family.
Under this option, comprehensive life coverage is paid out in fixed amounts to the nominee during the sudden demise of the policyholder at unexpected times
This option is like the income option except that the monthly installment keeps increasing by a fixed amount every year.
This option is a combination of the income and lump sum options.
Filing a claim can be challenging considering the emotional distress the beneficiary could be in due to the loss of the insured. Here are the steps to file a claim:
The beneficiary should reach out to the life insurance provider and provide necessary information through official modes of communication.
...Read More
To officially raise a claim the beneficiary will need to obtain the claim form from the life insurance company’s website or branch. Then the form should be completely filled with the required information.
...Read More
The claim form along with the required documents needs to be submitted to the life insurance company to process the claim. Post submission the status of the claim can be tracked through official modes of communication.
...Read More
Submitting the following documents along with the claim form is a vital step in the claim settlement process:
The biggest benefit of life insurance is that no matter your income level, life insurance ensures that your loved ones can make ends meet if you were to pass away.
Buying a life insurance policy at any stage in life gives you peace of mind. It offers a life cover that keeps you and your family protected in case of your unfortunate demise. The life insurance claim in the event of your death will help your family have a secure financial future, by paying for children's education, paying off debts and helping towards household expenses. The money you invest in life insurance is safe, and your family stands to gain from the benefits of insurance payouts in case of unforeseen circumstances.
Life insurance premiums are eligible for rebate for salaried persons to reduce their tax liability. Life insurance also gives you the benefit of taking a loan against the policy in certain cases. A life insurance policy will help you to plan your life goals, including your children's education, their marriages and your retirement corpus.
The riders available with your life insurance policy help you customise your plan and get maximum benefit.
There are different types of life insurance which help you reap the benefits of a secure future for yourself and your family.
It is a contract between a policyholder and the insurer wherein the insurer agrees to pay a certain sum of money in exchange for premiums upon death or maturity of the policy.
It can be done by forecasting future earnings, making a note of future annual expenses, calculating the future costs of financial goals such as children's education and marriage, and adding liabilities. Or you can also multiply your annual income by 10 for a rough idea.
You can find out the estimated cost of a potential policy with an insurance quote. It also contains other important details regarding the policy and the things that are covered.
Using the information on your insurance quote, you can determine that policy offers the best value by comparing it to quotes from other policies for the same or comparable coverage. If the policy is term life insurance, the term limits and coverage limits are usually included in life insurance quotes.
Anyone who has dependents to support and is an income earner for the household needs Life Insurance. Your loved ones who depend on your income would be negatively impacted by your untimely passing and the subsequent loss of income. A life insurance policy makes sure their financial future is protected through the payouts by the insurer in case of the insured person's death.
If you own a business, it helps to have life cover so that the business is not negatively impacted by your passing. It can help to sustain it by covering expenses and paying debts till your successor finds their feet in the business.
If you have taken loans during your lifetime, having a life cover will help your family to pay off your debts with the help of the payouts received against the insurance claim.
In India, we have a variety of insurance plans to suit every need.
The simplest plans are Term insurance plans, in which there is a death benefit but no maturity benefits. In Term Insurance, the insurer promises to pay the beneficiaries a lump sum amount in the event of the insured person's death. Some Term insurance plans nowadays also offer to give back the premiums you pay on surviving the policy period; these are called Term insurance with return of premium plans.
Other life insurance plans in India include Endowment Insurance plans, Unit Linked Insurance Plans (ULIPs), Moneyback Insurance plans, Whole life insurance plans, Group life insurance, Child Insurance Plans and Retirement Insurance Plans.
The main factor influencing the life insurance premiums of a policyholder is their age. Younger persons are generally considered healthy and unlikely to contract illnesses or pass away suddenly; hence younger people attract lower insurance premiums.
Gender is another factor that determines the premium amount as proven scientific and statistical evidence points to women likely to live an average of 5 years more than men. Consequently, since women are perceived to avail of policies for a longer tenure, they can avail of lower premiums.
Medical records play a crucial factor in deciding the premium as well, since life insurance policies typically come with an underwriting process that includes a thorough medical exam of the policyholder. Any red flags concerning physical health and potential illnesses can have an impact on the amount of premium to be paid.
Family history is important as certain hereditary diseases could be passed on to the policyholder. The family's medical history plays a part in revealing these patterns and can influence the amount of premium.
Smoking and drinking, which are considered harmful to health and can impact your longevity, also influence the amount of premium to be paid. Professions and lifestyles can also impact the life insurance premium. Persons working in professions considered dangerous like mining, oil and gas and fisheries, and indulging in risk taking activities like mountaineering can attract higher premiums.
Life insurance claims can be made either on death of the policyholder, on maturity of the policy or as a Rider claim. In case of death claim, the beneficiary who is the nominee of the policy should intimate about the claim to the insurer at the earliest by filling the intimation form which can be obtained from the nearest branch of the insurance company or can be downloaded from the website of the insurance company. Relevant documents like death certificate of the insured person, birth certificate of the insured person (for proof of age), the original policy document, and any other documents requested by the insurer should be provided.
The insurer is obliged to settle claims, once filed, within 30 days of receipt of all documents. In case further investigation is needed, the insurer gets six months to complete its procedures from the date of receiving written intimation of the claim.
If you are making a maturity claim, the insurer reaches out to the policyholder in advance with a bank discharge form, which the policy holder has to fill in and submit to the insurer along with the relevant documents requested.
In the case of rider claims, which are additional benefits accruing to policy holders for paying extra premium, duly filled claim forms and policy copies are to be submitted to the insurer. Different riders like Waiver of Premium and Critical Illness are settled through different means.
While deaths due to accidents are covered by life insurance, there are certain exceptions. Accidental death if the insured is involved in any criminal activity or if death occurs due to intoxication or drugs are not covered by term life insurance plans. Accidental deaths while the insured was engaged in adventure sports like sky diving and bungee jumping are also not covered by such plans.
Death benefits for suicide are generally made at the discretion of insurance companies. Usually, beneficiaries are entitled to 80 per cent of amount accumulated from premiums paid in case of a non-linked plan, and 100 per cent in the case of a linked plan, if the insured dies by suicide within the initial 12 months.
Term insurance plans do not cover death occurring from self-inflicted injuries, or due to illnesses like sexually transmitted diseases like HIV/AIDS.
Death due to alcohol or drug abuse is also not covered by term plans, nor is homicide where the policy holder is murdered by the nominee for money. Death due to an existing illness that has not been disclosed at the time of purchasing the plan is also not covered by term life insurance plans. Death caused by natural disasters like tsunami, earthquake, floods etc is not covered by term insurance, unless the policy holder has opted for riders for that purpose.
It offers benefits like tax benefits, financial security, financial coverage for families, wealth creation, retirement planning, the accomplishment of future goals, and much more.
Select the plan that fits your goal
The premiums are reasonable, your family will be financially secure in the event of your death and you may even add coverage for critical illnesses and accidental deaths.
It is possible for a family to achieve their financial goals as well as meet their day-to-day expenses by purchasing a term insurance policy. The dependants of the insured do not suffer financially if a term insurance is in place.
Accidental death is covered by a term insurance policy. The sum assured on a term insurance policy will pay out no matter what the cause of death is, whether it is a result of a health issue or an accident.
When term life insurance policy plans expire, the policyholder does not have to take any action. A policyholder will be notified that the policy is no longer in effect; no premiums are payable, and no death benefits would be paid out.
Death Benefits are paid to your dependents in a lump sum payment if you die unexpectedly. But few term insurance policies do provide a monthly income along with a lump sum amount to assist with regular expenses.
This is the sum of money you pay the insurance company in exchange for financial security. A monthly, semi-annual, or annual premium payment can be made.
Section 80C provides an income-tax deduction for ULIPs, and Section 10(10D) of the Income Tax Act exempts returns from income tax upon maturity. This policy offers a dual benefit.
If you invest in a ULIP for at least 10 years, you can expect a return of 10-12% per year.
ULIPs are best suited for people who have a long-term financial plan that includes both wealth creation and insurance.
ULIPs share four common features:
Option for Partial Withdrawal
Option for switching funds
Lock-in period required
An alternative long-term investment
Type | Risk | Type of Returns |
Bond funds | Medium | Low to medium |
Equity funds | High | High |
Cash funds | Low | Low |
Balanced | Medium | High |
ULIPs have a minimum lock-in period of three to five years, whereas traditional insurance plans are locked in until maturity. In addition, when you only want to insure, you must choose a traditional insurance plan. However, with a ULIP, you can get insurance while also increasing your capital.
A savings plan that takes you closer to your dreams and secures your family’s future.
Income tax1 benefits
Guaranteed4 benefits on maturity
Get return of total premiums paid13
Guaranteed11 income till age 99 years
Pay ₹50,000 for 10 years and get guaranteed ₹45,578 annually for 25 years12
ARN:ED/09/21/25571
We help you to make informed insurance decisions for a lifetime.
Reviewed by Life Insurance Experts
We at HDFC Life are committed to offer innovative products and services that enable individuals live a ‘Life of Pride’. For over two decades we have been providing life insurance solutions - protection, pension, savings, investment, annuity and health.
T&C*
37. Provided the policy is in force and all due premiums have been paid
38. 0% GST is applicable on all individual insurance policy premiums with effect from 22nd September 2025.
39. The above illustration is for a 25-year-old, healthy, non-smoker male who has purchased policy through HDFC Life website and has opted for Life option. Policy term and premium payment term is 40 years. Premium payment frequency is annual. Annual premium is Rs 8778 p.a. (Rs 24.04 per day) for the first year only. The annual premium second year onwards would be Rs 10,327 p.a. (Rs 28.29 p.a.)
ARN - PP/07/26/36624